Speaker 1 [00:00:00]
Bringing people around the idea of financial security for all, which is what FinCENCA stands for, is probably one of the noblest callings I've had in my career. Everything we look at goes through the lens of who does this help? Does it make it easier for people to get the financial advice, to get the financial products they need? I love getting to know people. I love getting to understand what makes them tick.
Helping people is a very rewarding thing. the rule of law in our courts, the deep capital markets, the 2 oceans that separate us from a lot of the dangers in the world. There's just so much about this country, objectively and subjectively, that make it such an incredible place to grow up, raise a family, start a business, live your life. It's something I will never change my mind about, no matter how difficult things get in Washington.
Speaker 2 [00:00:52]
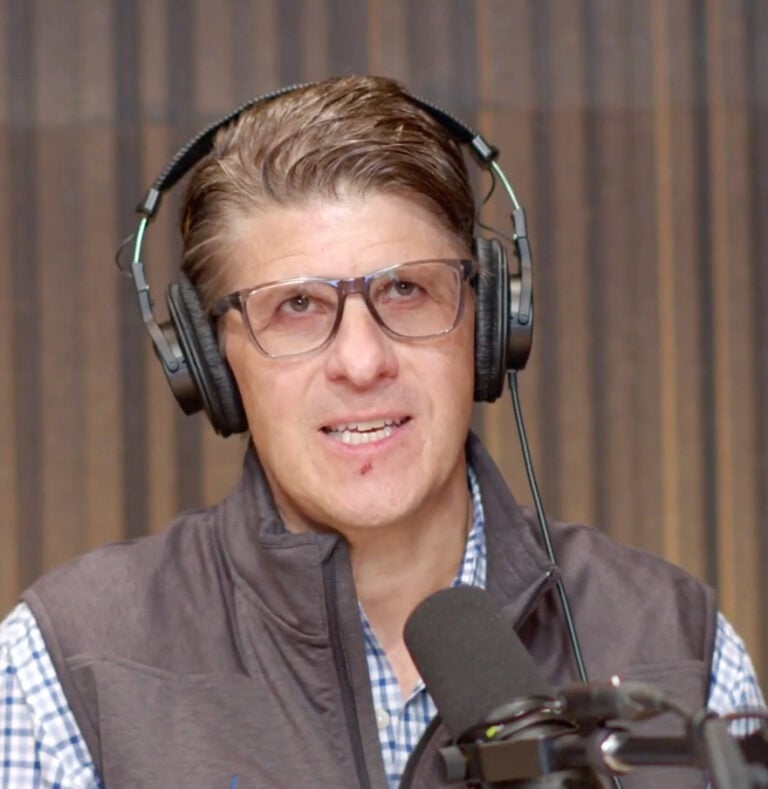
We're living longer, and wealth is changing hands at a record level. Planning for retirement is becoming ever so more complex. For Bob Chalhous, that makes one thing incredibly clear: financial security can't be left to chance. Bob is the Chief Advocacy Officer at FinCENCA, an organization working to help more Americans build and protect their financial future.
Today we're talking about the challenges putting financial security under pressure, the opportunity they're creating for the profession, and why the way we plan for the future may need to change. I'm Fred Fuller, and welcome to another episode of CEO Behind the Scenes. Bob, how are you?
Speaker 1 [00:01:36]: I'm doing great, Fred. Great to be with you. Yeah,
Speaker 2 [00:01:38]
it's great to have you. So we're going to jump right in here. There's a lot of talk in the media, and I, and I sometimes wonder if this particular term isn't yet overplayed just a little bit in many, many different applications. But the idea of the perfect storm around financial security, what's coming together right now and why does it matter to the average person?
Speaker 1 [00:02:01]
Well, it matters to the average person because every American citizen is actually eligible to sign up for Social Security. And in 2032, the Social Security Trust Fund is set to go insolvent, meaning that it will be taking in less money than it's putting out. And if Congress and policymakers in Washington don't do anything, there will actually be a 23% cut in benefits.
So if you're either on Social Security or somebody getting ready to apply for Social Security in 2032, you're going to be potentially facing that cut. The other thing that's on the table with respect to the perfect storm is, you We're in a rising debt environment. In the last 10 years, the debt has doubled from $20 trillion to $40 trillion, and that debt needs to be serviced by taxpayers.
And that means every taxpayer, part of the money that they send to Washington is going to pay the debt. And that's money that's not there either to fund Social Security or to fund Medicare, which is also on track to a deficit. And so big issues there that affect the very the very funds that Americans are relying on, not only for their financial security, but also for their health security in retirement.
Speaker 2 [00:03:22]
It feels as though this has got some demographic components, right? People are aging and living longer, and you have greater longevity changing the way we need to think about financial security. I mean, it kind of feeds into that perfect storm thing. But so demographics are critical, this conversation?
Speaker 1 [00:03:40]
Definitely, people are living longer lives and they're not necessarily living healthier lives. You know, the average age over the last decades has increased quite a bit.
And how that- the rub on that from a financial security perspective is that we have seen a big move away from defined benefit plans, plans that pay you a certain amount of money every month for the rest of your life, to more of a defined contribution plan where the money that's gone into your 401 or your IRA is the money that you have to rely on for the rest of your life, and it's not necessarily parceled out in a way that you can make sure it lasts.
And that's part of the anxiety that it creates for a lot of Americans about running out of money in retirement, compounded by these issues with federal entitlement programs, creates a potentially scary situation for people.
Speaker 2 [00:04:34]
So in all of this, we've been talking for, I don't know, maybe all of 90 seconds or a couple minutes now, and already I'm like, I need financial advice. Like, holy smokes, right? So the demand for financial advice has got to be overwhelming out there. And what are some of the bigger opportunities emerging for the profession?
Speaker 1 [00:04:56]
The need for financial advice has never been greater, but we actually have a shortage of advisors right now. There's a McKinsey estimate that says there are a shortage of 100,000 advisors just over the next 10 years to fill the need of the advisors currently serving Americans. And the importance of an advisor is so that you can have a financial plan. Of course, you can go online. Of course, you can go on ChatGPT.
Of course, you can listen to the advertising coming at you from every direction on TV and social media. But at the end of the day, you really want to talk to a professional to give you the advice that you need. And Our profession is a big believer in holistic financial planning, meaning that there's not just one way to do it.
The hallmark, the North Star of FinCENCA, is the EY study, which shows that a combination of life insurance, investments, and annuities get Americans the best results. Annuities are particularly important from the standpoint that an annuity is one of the only, or the only product other than a a pension or Social Security that can guarantee you a certain amount of money every month the rest of your life. And so it's a good way to reduce some of the risk.
And so being able to get out there and communicate with Americans about the importance of having a financial plan, of having a holistic financial plan, is really important. You know, Americans have done an incredible job saving money. If you look at the growth in 401s and IRAs since 2000, it's been huge. And people have really done a good job putting money away.
And now we're getting to that point in people's lives with the baby boomers retiring and Gen Xers right on the edge retiring as well. They need to be able to figure out a way to spend that money and use that money in a way that makes their lives better and provides them some enjoyment. rather than being worried about it. And that's why having a financial plan is so important.
Speaker 2 [00:07:03]
Are there things that the financial security profession can do beyond the planning to be a part of this solution?
Speaker 1 [00:07:12]
Yeah. You know, being engaged, being engaged in your community, being engaged with your policymakers is a really important part of it. You know, these solutions that need to take place around entitlement programs and the debt, are not going to happen on their own.
And while we aren't offering any solutions as an industry to Social Security or the debt or the deficit, I think it's very important that financial advisors and all Americans communicate with their elected officials at the state and local level as well as at the federal level how much they're paying attention to how Washington and the states are looking out for their best interests in retirement.
Speaker 2 [00:07:55]
Some component of get involved, right? Have a voice, vote, right? Some of the basics. Speaker 1 [00:08:01]: Vote, send a letter, be engaged is really what it's all about.
Speaker 2 [00:08:07]
Yeah. You know, it's funny because I think when people consider their financial advisors and their financial futures, I would hazard a guess that a lot aren't thinking about that. A lot of individuals, like when you're interviewing somebody for this role in your life, You're not thinking how active are they civically or politically. And the reality is in this day and age, it's- you don't have to- I mean, there's limits, but you need to be involved.
Speaker 1 [00:08:35]
Yeah, you need to be involved because there are- and part of the reason people need to be involved is because there are always changes happening in Washington and in the states, whether it's around actual entitlement policy or retirement savings policy. In Washington over the last 30 years, there have been a number of things that Washington has done to expand the availability of 401s and IRAs. IRAs. There have been a lot of efforts around expanding access to long-term care.
There's been access to create these streams of income that people could get through annuitization. And, you know, people need to have access to the best and latest information, and then they need to have somebody to talk to it about, and that's a financial advisor who offers holistic planning.
And look, you know, with respect to life insurance, a lot of people don't want to talk about life insurance because Life insurance means you may not be here, but, you know, one of the things people need to plan for is protecting their family, either in the short or the long term.
Speaker 2 [00:09:37]
And many of these vehicles, right? So life insurance, disability income, long-term care coverage, a lot of these actually come together to help alleviate some of the burden on the public programs.
Speaker 1 [00:09:50]
Exactly. And the savings runs into the billions of dollars a year. And so by, by people taking advantage of the tax- in some cases, tax incentives of these programs, by people taking advantage of them. In part, they
are saving the federal government and the states who often pick up the cost through Medicaid from having the money to be there for the people who really do need it. Yeah.
It's an important thing for people to think about, not only as they get older, but As soon as they're working and drawing a paycheck.
Speaker 2 [00:10:29]
And that number you mentioned, billions, I'll put a point on that for you. It's roughly $120 billion a year. So it's not an insignificant amount of money. It's not $1 billion or $2 billion on trillions. It's $120 billion. It's real money. Very, very
Speaker 1 [00:10:47]: real. It is very, very real money fraud.
Speaker 2 [00:10:50]
And I think it's really important as we have this conversation, You start thinking about, well, it's relieving some public burden. I can see a response of, yeah, but it's their responsibility to do that. And in the end, there's kind of a component of, and I'd love to hear your thoughts on this, there's kind of a component of it doesn't really matter what you think.
At the end of the day, you're trying to make sure that you have a secure financial life, that your loved ones do. And so, we wouldn't get caught up on relieving the burden so much as making sure that you have what you need for your life, right?
Speaker 1 [00:11:27]
Yeah. This is what we call a win-win situation, Fred. You win, the government wins, the taxpayers down the road win because maybe these programs have a little bit less of the burden.
But leave no mistake, policymakers are going to have to act with what we discussed about longevity and this decline in the defined benefit plans, you know, there's going to have to be some action in order to ensure the solvency of these programs for the long term so they're there for the people who really need them.
Speaker 2 [00:12:00]
And if we look at the great wealth transfer, right, retirement security and long-term care as multi-decade trends, how does the role of financial advisor need to evolve? as there's so much change in the market?
Speaker 1 [00:12:16]
Well, it's really important, number one, that if you or a family member is going through this sort of wealth transfer, and when we talk about the billions of dollars, we're not just talking about quote-unquote rich people. We're talking about that couple that maybe saved $100,000 or $200,000 or $300,000.
And, you know, protecting that asset for the next generation is important because that can be the seed money to help buy a house, send somebody to college, take care of some medical bills, pay off some debts. And so when you think about the transfer, it's not a static thing. It's about how do you best provide for the next generation rather than just take the money out and go to Hawaii, which I'm all for going to Hawaii.
Hoping to do so someday myself. But that ability to have a little discipline and set things aside, and that's where a financial advisor can really help because they can help you do both things. And I think the thing that people need to never underestimate is compounding, the magical effect of compounding, whether through interest or through the markets.
It is what a little bit put away today can be a lot tomorrow, and that's why getting started when you're younger rather than waiting till you're older is just so important.
Speaker 2 [00:13:39]
It really is. Interesting to consider how people view this, right? When you talk about Hawaii, right? Like, yeah, who doesn't love Hawaii? We all love Hawaii. But there's a real pragmatic thing to it around, yeah, that's an extreme example, but that money might be moving through the generations and those generations will have different needs. Right? You can, you can- maybe somebody's got a health concern that would really help them a lot.
And so, they're going to need a different plan than somebody that's, you know, 26 years old, graduated college, and ready to take over the world, right? So, different plans for different people at different times, with Hawaii being way, way, way on the back burner.
Speaker 1 [00:14:28]
Yeah. Well, you know, it's estimated that 70% of Americans are going to need long-term care, and nowhere near 70% of Americans are prepared to fund their long-term care. And that's why setting those priorities for the unexpected, those funds away for the unexpected that can come along is just so darn important.
Speaker 2 [00:14:48]
Yeah, that's crazy. And so, you know, it's funny, we just- I just mentioned somebody out of college setting the world on fire. But I don't think this particular thought that I'm about to share here is specific necessarily to college grads. I think it proliferates regardless of where you are in your career, college grad, not college grad, right? Whether 20 years in or wherever you are.
But there are a lot of folks that say, well, I've got a couple of investments, so I've got a plan.
Speaker 1 [00:15:17]
Well, it's better to have a couple of investments than not have any investments. But if you have a plan, that gives you a roadmap. It's kind of like getting on the road and saying, yeah, I want to drive across the country, but I'm not exactly sure how I'm going to get there and I don't have my phone and I don't have my GPS. I don't have an old-fashioned map, so I'm just going to kind of wing it.
And you may end up going the wrong way. You may run into a few cul-de-sacs. You may meet some car accidents along the way that have traffic backed up. And so if you have a map, you can get there in the quickest, most efficient way and in a painless manner.
And so that's kind of what a financial advisor can help you do, and somebody who's helping give you the rules of the road so you don't have to make them up as you go along.
Speaker 2 [00:16:09]
So, when we talk about plans in the other part of my life, and people, I think, are pretty quick to loathe creating plans, they're pretty quick to denounce the administrative burden that it is to create a plan. And I always tell people, it's like in the cartoons, you know, when the pirate gets the map to the treasure and it's the dotted line and there's the X at the end, like, that's what the plan is.
The plan shows you how to get to the X, and that's what we're all trying to do, right? So take your time, invest, create a plan, and you'll find the X and it'll be far more rewarding.
Speaker 1 [00:16:48]
Yeah. And it's about a little bit every day. It's about incremental. It's not about all one fell swoop winning the lottery, which if you do win the lottery, just make sure you set some of it aside. But it's really about what you put away every day or every week and making those daily decisions about your spending and making those daily decisions about what's really important to you.
And I'm not saying that people should forego experiences and travel and even trips to Hawaii with their family. Don't do that. But think long and hard about buying things and whether that actually gets you to where you want to go or is it just more of an impulse purchase.
Speaker 2 [00:17:29]
Yeah, and if you win the lottery, call me. I'll put my phone number out for that one, but only if you win the lottery. No, um, when- how should- how soon or when should somebody start talking to a financial advisor?
Speaker 1 [00:17:45]
I think as soon as you, um, as soon as you start working and drawing a paycheck, um, and are, you know, you're paying rent, um, you may be starting a family. You may have just finished college, so maybe you're paying student loans.
I think one of the barriers to people finding a financial advisor is that they always think it's going to cost them a lot of money and they don't necessarily think they have enough money to make it worth that advisor's while.
And there are plenty of advisors out there who think for the long term, plenty of advisors just starting out in the business who would love to work with people not just on their savings and the money they're putting away or the money they're putting away for their life insurance, but also on their spending side of the equation and how they're using their money and helping them manage their debt.
So there are financial advisors for everyone, no matter whether you're at the top of the economic ladder or the bottom of the economic ladder or somewhere in between. And so Making the phone call, asking for help, and finding that person that can kind of tune you into what you need day in and day out or week in and week out is really important. And again, starting small, there's nothing wrong with starting small.
Speaker 2 [00:19:06]
You know, there's certain things in life that for some reason I think the human species has an aversion to. And it really and truly is. It's like exercising. Look, everybody knows and everybody in the world knows, like, go out and walk 2 blocks. Like, most people can do that. You don't have to run a marathon. How many people do it, right? And I fight it like nobody's business. Eating right. This is one of those of like, just go do something.
Don't wait until you have X amount saved up or that you fit into a bucket or that some friend told you to check this box and make- just go do it.
Speaker 1 [00:19:43]
Right. Exactly. Just go do it, whether it's you're putting money in your savings account or you're finding a few places to save on your streaming subscriptions or your app subscriptions, going through and talking to other people who you know, talking to your friends and asking them for their advice, talking to your family, talking to your parents' family and asking them how they got started investing and saving for their future.
The beauty is that there are life insurers and other financial advisors all over the country. In almost every county in the country, you can find somebody to help, but you've got to ask. It's like a lot of things in life. If
you don't ask, nobody's going to help you.
Speaker 2 [00:20:34]
Yeah, just go do it. People's feet just get stuck on the flypaper and you're like, man, just go do something. But let's take a moment here and shift gears and talk a little bit about Finsecca, if we could.
Speaker 1 [00:20:48]: Okay.
Speaker 2 [00:20:49]
Right? 9 organizations have been integrated over the past 5 years. Membership has grown by an average of 23% a year over the last 4 years, and it's approaching 15,000. What has that experience taught you about bringing people together around a shared mission?
Speaker 1 [00:21:08]
Wow. It's taught me that it requires a lot of work and it requires a lot of communication. But bringing people around the idea of financial security for all, which is what FinCENCA stands for, is probably one of the noblest callings I've had in my career.
And we're doing our best to make sure we're not only serving our members who are again, number close to 15,000, from advisors through independent brokerage through agency leaders through distribution people at the various companies that sell insurance products. We also care about their customers and their clients because they do. And everything we look at goes through the lens of who does this help? Does it make it easier for people to get the financial advice, to get the financial products they need?
And that's our advocacy mission and my major role at FinCENCA is what do we need to do to clear the roadblocks both at the state and federal level, whether it's onerous regulations or legislation that could make things a little bit easier for an advisor to provide advice. or to help somebody roll over their 401 into an annuity.
We look at all those pieces and pull them together in a way that we can get all of our members on board and go talk to members of Congress, go talk to policymakers in the states, go talk to regulators, whether it be at the SEC or the Department of Labor or the Department of Treasury. And Fill them in on what we're doing.
And we get behind things where we support them, and we also get out in front of things where we think the policy is headed in the wrong direction. And that is- our 2 major pillars are either educating or advocating. And in many ways, we do both at the same time, trying to advance the cause of financial security for all.
Speaker 2 [00:23:19]: What drew you to this work?
Speaker 1 [00:23:21]
I started in politics 40 years ago when I was in college. I had planned to go to law school, and I fell in love on a political campaign. I came to Washington like a lot of young people do to work for my member of Congress, and that led to a 16-year career working on Capitol Hill and working on political campaigns across the country. I love that work.
I was able to transfer that work into moving from a government paycheck to a private sector paycheck about 20 years ago. And so for the last 20 years, I've been working in this space. I've worked at a large financial services firm, a large accounting firm. This is the latest stop. on my docket, and we're a nonprofit trade association. I think what really draws me to it at the bottom line is the people. Every person's different.
You can't judge people as a group. You have to take them one at a time, and I love getting to know people. I love getting to understand what makes them tick. One of the things I've also found is that helping people is a very rewarding thing.
And though I'm not volunteering in a soup kitchen or picking up garbage or those things that a lot of people do that are very public service oriented, engaging individually not only with our members but doing things that really help their clients leaves me with a good feeling at the end of the day and helps me sleep at night.
Speaker 2 [00:25:03]
It's such a critical component of everybody's security. Right. I mean, you can say what you want. I had this conversation with a relative of mine about, you know, what do people worry about the most? And I think it's, you know, it's, this is one of the biggest ones. You could argue whether it's 1, 2, or 3, but it's up there. No denying that, right?
And so, yeah, it seems like it'd be a pretty powerful place to be able to help people with something like this. You know, in thinking about the growth of Finseca and coming back to that for a moment, What have you had to protect or reinforce when you bring, you know, how many, 9 organizations together? It's real easy for your message and your mission and your ethos to get a little bit cloudy or nebulous.
So, what are a few of the things that you really had to dig in on, if any?
Speaker 1 [00:25:55]
Well, you know, there is always the desire in Washington to raise revenue. And when they do so, they are looking at all kinds of different individuals and industries, and our industry and profession is not immune from policymakers looking for revenue that comes from the benefits that are provided to the customers of our advisors. And so protecting those benefits and expanding them is really a huge part of the huge part of the job.
The other part of the job is as much on the regulatory side and removing a lot of the friction around our ability to get products to people who need them, to get the right product to the right person, because if you create too much legal risk for people to sell a product, they're probably not going to do it, and that means somebody's not getting a product that could be really beneficial to them.
So a lot of it is raising awareness, removing hurdles, and coming up with new ideas and supporting other people's ideas. And we work very closely with a number of trade associations and very closely with our corporate partners in the life insurance industry to find consensus around big ideas that can push financial security for Americans in the right direction.
Speaker 2 [00:27:25]
And if you look out over the next 10 years, and I mean, that's insane to think that anybody could predict absolutely anything in 10 years. I'm going to have a talk with my copywriters here. It
Speaker 1 [00:27:40]
feels like time is racing by in this world of AI. 10 years is like 100 years.
Speaker 2 [00:27:47]
It's dog years, man. What do you see as the future in this space? What excites you?
Speaker 1 [00:27:53]
I think the future's bright. Now, I'm generally an optimist, but I think the future's bright. I think healthcare, I think technology are all doing a ton to increase people's awareness, to increase their health. I think those are things that make me feel good. What doesn't make me feel good is The current fiscal situation in the United States around the debt and deficits, as well as the situation with Social Security that we talked about, and also the political polarization.
But at some point here in the not too distant future, including the senators elected in this election, they're going to have to deal with this. And I think that is going to be the big challenge. And do we all as Americans rise to that occasion? I am proud to say I think we will. We always have in this country. It's not always easy. Democracy is messy sometimes. Some people refer to it as sausage making.
You don't really want to see it going on, but you generally will be happy with the end product. And I feel very good, and I think we'll end up in the place we need to be, but it's going to require a lot of work, both from the American people and from policymakers, so that the decisions that need to get made get made.
Speaker 2 [00:29:16]
And it's important that we have people like you driving such conversations and causes, right? And you have a world of people, peers, counterparts, people on the other side of the coin of whatever your side is, right? It's a world of individuals that push and drive these things forward and in a collective way. continue to create a healthy environment for the rest of us.
Speaker 1 [00:29:43]
That is indeed the case. And while we all may have different ideas about what works best, and sometimes those differences fall along party lines, sometimes they're within the different political parties, I think everybody wants to get to the same place. It's just a matter of how we do it. And that's part of the sausage-making of the legislative and political process. It's why it's so important that people are involved in elections.
It's why it's so important that people know who their congressman is and their congresswoman, and they know who their state legislator is, because they're the ones that can really drive the decision-making and raising the profile of issues that need to be made a priority.
Speaker 2 [00:30:25]
Yeah, we can do a bipartisan public service announcement right now, and that is go vote. Go vote. Speaker 1 [00:30:32]: Exactly. Go vote. Exactly.
Speaker 2 [00:30:33]: No matter who you vote for, go vote.
Speaker 1 [00:30:35]: Yeah,
Speaker 2 [00:30:36]: go vote,
Speaker 1 [00:30:36]: participate. No question about it.
Speaker 2 [00:30:38]
Okay, so now we're going to shift gears a little bit, and, uh, and we have 2 questions that we ask of everybody on the show. The first question is, what's one thing you've changed your mind about recently and why?
Speaker 1 [00:30:52]
I used to think that I could really direct the lives of my teenage daughters. I used to think at this point in their life when they're getting ready to go to college and making big decisions that I would have some ability to influence the direction they're going. I also thought I would have the energy to do it. I've decided I am completely wrong.
All I can do is give them the best guidance I can knowing that they may or may not be listening to me. And it's their life, it's their decisions, it's their choices, and they're the ones that are going to have to live with it. And that's been a big jump for me. I'm somebody who is a bit of a- I don't want to say a control freak, but definitely a micromanager at times. So that's the one I'm picking.
Speaker 2 [00:31:45]
Here's the other side of that is what's one thing you've not changed your mind about and you believe you're right? Like others are saying, no, it's not that way. And you're like, no, I'm telling you you're wrong. Like, what's one of the core beliefs that you have that others see a little differently?
Speaker 1 [00:32:01]
I love this country and I believe it's the best country in the world. And despite all the problems and difficulties and challenges and disagreements we have, every time I travel around the world, and I don't do a lot of travel, but when I do travel around the world, I can't wait to get home. It's why people come here. It's why people start businesses here.
The rule of law in our courts, the deep capital markets, the 2 oceans that separate us from a lot of the dangers in the world. There's just so much about this country objectively and subjectively that make it such an incredible place to grow up, raise a family, start a business, live your life. It's something I will never change my mind about no matter how difficult things get in Washington. That will be my true north.
Speaker 2 [00:32:50]
Check out FinCENCA. Financial advisors, go as early as you can in the course of your career and your savings plan. Make sure that you explore all your options. You know, Social Security is- it will be impacted by the year 2030. There will be an impact to the contributors and participants.
And so it's incumbent upon every one of us to work with a financial advisor to create that plan to the magic X and make sure that we have the financial security that we need and that we deserve for us and for our loved ones.
Speaker 1 [00:33:27]
Very well said, Fred. It's been great being here with you today, and thank you for having me on.
Speaker 2 [00:33:32]
Excellent. Thank you so much, and we'll talk again soon. For Bob Schellhaus, I'm Fred Fuller. Thank you for listening. Go like, subscribe, do all that good stuff. Let us know that you're listening, and we'll see you next time on CEO: Behind the Scenes.



 16


 Host
 POPULAR TOPICS
 FEATURED PODCASTS


 Home

 Podcasts

 Covers

 Community

 Sign In